There’s a risk the ongoing French bond rout escalates into a euro-area debt crisis that eclipses the blowup that began in Greece nearly two decades ago, warned Franklin Templeton’s fixed-income investment chief.
“I don’t think anyone is really ready for a eurozone debt crisis version 2.0, and this one could be significantly worse if it were to come to pass,” said Sonal Desai, global chief investment officer at Franklin Templeton Fixed Income.
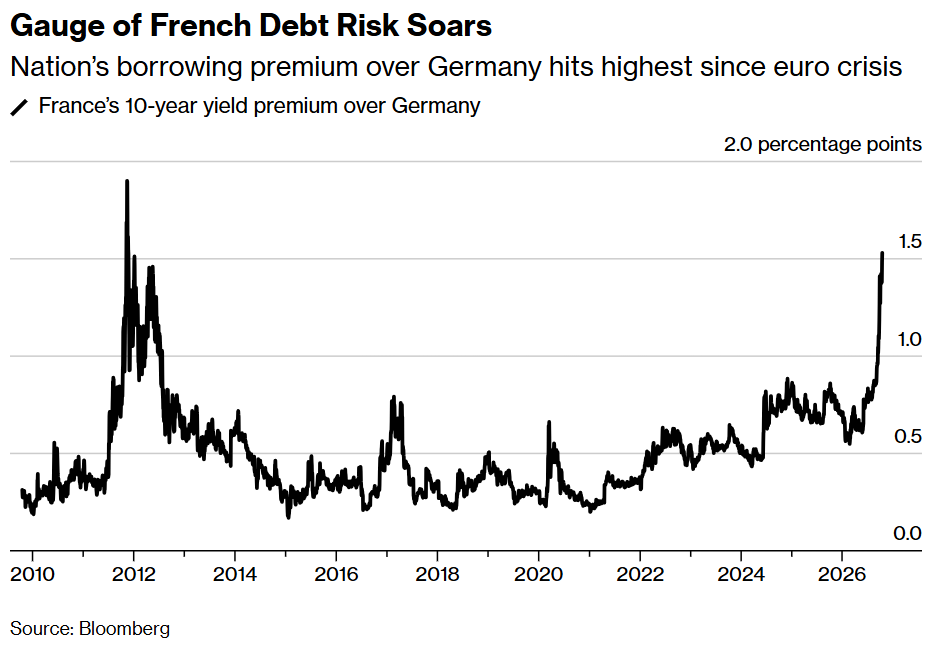
While that scenario is yet to materalize, Desai’s concern reflects the recent direction of travel for French borrowing costs alongside the nation’s status as the second-largest economy in the bloc. France’s 10-year yield premium over German debt — a closely-watched risk metric — closed above 1.5 percentage points on Tuesday for the first time since January 2012.
That was close to the height of the region’s sovereign debt crisis, which centered initially on Greece before spreading to the likes of Ireland, Portugal and Spain.
As a founding member of what became the European Union, France has the potential to be a bigger stress test, according to Desai. It’s a €3 trillion economy with about €3.6 trillion in debt.
“France has more than 10 times the debt that Greece had. A simple bailout is not on the cards,” she said at the Franklin Templeton Fixed Income Forum.
That said, there are differences between then and now. France is still an investment-grade rated borrower, and banks — big holders of French sovereign bonds — are better capitalized than in 2010. The European Central Bank has also showcased its ability to tame bond-market turmoil over the years.
Desai said Franklin Templeton’s bond portfolios were skewed toward shorter-duration assets in Italy and France, in contrast to a more constructive view on Spanish and German debt.
“We shouldn’t underestimate the potential for significant volatility coming out of the eurozone,” Desai said.
Written by: Alice Atkins and Greg Ritchie @Bloomberg
The post “Franklin Templeton Sees Risk of Euro Debt Crisis Worse Than 2012” first appeared on Bloomberg